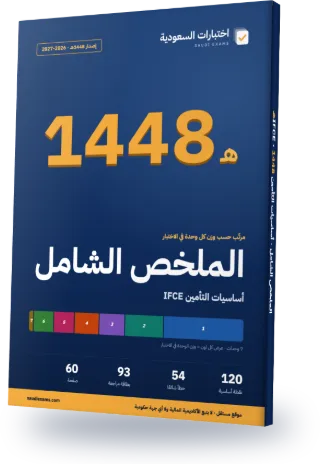
IFCE Insurance Foundations Complete Review Guide 2026–2027
Every exam topic in a 60-page Arabic PDF, ordered from the heaviest unit to the lightest. The first three chapters alone cover about 66% of the exam questions.
- 60Pages
- 120Key points
- 54Common mistakes
- 93Flashcards
Guide map
Each chapter is one exam unit, ordered by its weight in the real exam.
| Chapter | Unit | Weight | Exam questions | Key points |
|---|---|---|---|---|
| 1 | Understand the main legal principles governing insurance contracts | 36% | 36 | 18 |
| 2 | Understand the nature and main features of risk and insurance | 18% | 18 | 18 |
| 3 | Understand the main regulatory and legal principles applicable to insurance business in Saudi Arabia | 12% | 12 | 18 |
| 4 | Know the main insurance products and related services | 12% | 12 | 18 |
| 5 | Know the structure and main features of the insurance market in Saudi Arabia | 10% | 10 | 18 |
| 6 | Understand the procedures and policies of the insurance process | 10% | 10 | 18 |
| 7 | Know key aspects of ethical behaviour and corporate governance | 2% | 2 | 12 |
Chapter 1 in full: Understand the main legal principles governing insurance contracts
36% of the exam, about 36 questions. These are its key points, as in the guide.
- An insurance contract is a legally enforceable agreement between the insurer and the policyholder: the policyholder pays the premium and accepts the terms, and the insurer pays a sum when a specified event occurs. The key elements of a valid contract are offer and acceptance and consideration (the premium is the policyholder's consideration), plus the intention to create legal relations and capacity. On capacity: minors have limited contractual capacity governed by Sharia and the Civil Transactions Law; a contract made by a person with a mental illness is generally valid unless the person could not understand its nature and the other party knew; an undischarged bankrupt can contract but the ability to perform is affected by the bankruptcy (3.1, sections 3A and 3C-3E).
- An effective acceptance must be final and unconditional; a conditional acceptance is a counter-offer that rejects the original offer, and no contract exists until the first party accepts it without conditions. A person who did not know of an offer cannot accept it. Where the parties agreed to use the post, acceptance is complete when the letter is posted, even if it is lost (3.1, section 3B).
- Cancellation: the insurer's cancellation must follow the policy's conditions, with written notice to the customer citing the clause and the reasons (Article 57 of the Insurance Market Code of Conduct), and amounts due must be paid without undue delay (Article 58). In most classes the policyholder may cancel at any time and recover part of the premium (pro rata or at short-period rates) if there are no claims; the main exception is travel and other policies of under one month (3.2, section 3F).
The rest of chapter 1, on this page
- Other ways a contract ends: expiry and performance, total loss of the subject matter (the policy ends automatically), and avoidance. A void contract has no effect (fundamental mistake, illegality, no insurable interest); a voidable one may be avoided by the insurer for non-disclosure, misrepresentation or breach of a warranty, which must be complied with strictly. On a fraudulent claim the insurer does not pay, may recover what it paid, and may end the contract from the date of the fraud without returning premium (3.2, section 3F).
- Agency: a relationship in which the principal authorises the agent to bring the principal into a contract with a third party. It arises by agreement (the most common in insurance), by necessity, or by ratification. Authority is actual (express or implied) or apparent (a third party reasonably believes the agent has authority); the principal may be bound where the agent's act is normal for that trade or profession. It ends by agreement, by either party ending it, or by the death, bankruptcy or loss of mental capacity of either party (3.3, section 3G). An independent intermediary is the insured's agent when advising on cover, on which insurer to use or on how to claim, and the insurer's agent when authorised to receive proposals and confirm cover, inspect property or collect premiums. Once the intermediary collects the premium for the insurer, the insurer is the principal (3.3, section 3G).
- The agent's duties to the principal: obedience, personal performance (duties are not normally delegated), reasonable skill and care, good faith, and accountability (keeping proper records of money and transactions). The principal's duties: pay remuneration (usually commission as a percentage of premium), indemnify the agent for expenses and losses properly incurred on its behalf, and accept the consequences of the agent's acts within the scope of authority; the principal must notify interested parties when the agency ends (3.4, section 3G).
- Terms of business agreements (TOBA) between insurer and intermediary must be clear and concise, reflect the working relationship, allocate responsibilities and rights, and ensure compliance with rules. They cover appointment, authority and prohibitions, compliance responsibilities, commission, passing on material facts, premiums and credit, termination, arbitration, Saudi law and jurisdiction, and the Arabic text prevailing in case of difference (3.4, section 3H).
- Insurable interest is the legal right to insure arising from a financial relationship, recognised by law, between the insured and the subject matter of the insurance. Its features are the subject matter, the legal relationship and a financial value that can be estimated (not sentimental value). The insured's interest is the subject matter of the contract. It arises at common law (ownership or avoiding liability), by contract, or by statute. Examples: a part-owner, a bailee, a tenant and an agent; a shareholder has no interest in company assets, and a mere expectation of inheritance is not enough (3.5, sections 4A and 4C).
- Timing of insurable interest: in protection and savings it must exist at the start of the policy and need not exist at the time of loss; in marine it must exist at the time of loss, with a reasonable expectation enough at inception; in general insurance it is expected when the policy is issued and is required, without exception, at the time of loss. If there was never an interest the policy is void. An insurer has its own insurable interest, which allows it to reinsure (3.5, section 4B).
- The principle of utmost good faith binds both parties: the proposer must disclose all material facts before the contract, at renewal and on mid-term changes (endorsements), and the duty continues throughout the policy only if the policy says so (for example motor, commercial property and liability). In long-term protection and savings, the duty ends once the policy is in force. The insurer must not withhold discounts, impose undiscussed non-standard terms or mislead the customer (3.6, sections 5A and 5B).
- A material fact is anything that would influence the prudent insurer in deciding whether to accept the risk, and on what premium and terms; it relates to physical hazard (building construction, driver's age) or moral hazard (criminal convictions, prior refusal of cover). There is no need to disclose: matters of law, risk-reducing factors, what the insurer should already know, what the insurer has waived, what the proposer does not know, and matters dealt with by the policy terms. For individuals, only what an ordinary person would consider relevant is expected (Article 42 of the Code of Conduct) (3.6, section 5C).
- Consequences of non-disclosure and misrepresentation: the insurer may avoid the policy from inception, decline the claim, or adjust premiums and terms. In commercial insurance remedies are available whether the misrepresentation was fraudulent, careless or innocent; for individuals, an honest and reasonable misrepresentation may leave the insurer obliged to pay, a careless one lets the insurer act as it would have done on accurate answers (for example excluding the condition), and a deliberate or reckless one allows the whole policy to be avoided and all claims refused. In compulsory motor insurance (bodily injury and third-party property damage) the insurer is normally not allowed to escape liability to victims (3.6, sections 5D and 5E).
- Proximate cause is the dominant cause that sets off the chain of events and is directly linked to the loss; it is not necessarily the first or the last. Once identified, the insurer classifies it as an insured peril (named in the policy), an excluded peril (stated as not covered) or an uninsured/unnamed peril (not mentioned at all). The claim is paid if the proximate cause is insured and declined if it is excluded; the principle can be modified by the policy wording (3.7, sections 6A and 6B).
- Indemnity is a financial payment sufficient to put the insured, after the loss, in the same financial position as immediately before it. Most general insurance policies are indemnity policies (property, liability, business interruption); benefit policies (personal accident, sickness, chronic illness, hospital cash) pay a fixed sum and their benefits can be added together. Settlement options are cash, repair, replacement or reinstatement; if the policy is silent the insured has a legal right to a cash payment. For property, indemnity is measured by the cost of repair or replacement at the time and place of loss less wear and tear; for liability, by the court award or settlement plus costs (3.8, section 7A).
- Modifications of indemnity: (1) new for old (home contents, machinery): wear and tear is not deducted; (2) reinstatement (reinstatement memorandum: the sum insured must be at least 85% of the actual value or the claim is reduced; day-one reinstatement: the policyholder must state the amount accurately), with the benefit only if the property is actually reinstated; (3) agreed value: fixed at inception, so the loss is not valued at claim time (common in marine and works of art); (4) first loss: a sum insured below the total value. Recovery is also limited by the sum insured, internal limits and single-item limits (3.9, sections 7B-7D).
- Underinsurance means the sum insured is less than the actual value. Average applies to partial losses and treats the insured as their own insurer for the shortfall: payment = sum insured ÷ actual value of the property at risk × loss (example: 600,000 ÷ 800,000 × 100,000 = 75,000). It applies to commercial fire and theft and to home insurance, but not to liability insurance. An excess (deductible) is the first part of each claim not covered by the policy (compulsory or voluntary in exchange for a premium discount) and is deducted after average is applied; a large deductible is a big amount, common in commercial insurance, taken out of the policy limit (3.10, section 7E).
- Contribution is an insurer's right to share the cost of an indemnity payment with another insurer, and it applies only to indemnity policies. Requirements: two or more indemnity policies covering the same insurable interest, the same peril and the same subject matter, each liable for the loss, with none containing a clause preventing contribution. Rateable proportion = the policy's sum insured ÷ total of the sums insured × loss (example: policies of 300,000 and 600,000 and a loss of 270,000 pay 90,000 and 180,000). With no contribution clause the insured may claim the full amount from any insurer, which then recovers the other shares; if both policies contain non-contribution clauses they cancel each other out (3.11, sections 8A-8C).
- Subrogation is the insurer's right, after paying the claim, to step into the insured's shoes and recover what it paid from a third party responsible for the loss, up to the amount paid, bringing the action in the insured's name; anything recovered above the amount paid goes to the insured. It can arise from tort (civil wrong), breach of contract, statute, or the subject matter (salvage: on a total loss the insurer owns what is salvaged and sells it). It is prevented where the insured has no rights against the third party (for example an exemption-from-liability clause), in benefit policies (such as personal accident), when the insurer waives it (for example against a parent or subsidiary of the policyholder, usually for extra premium), and normally against negligent fellow employees (3.12, sections 8D-8F).
Common mistakes in this chapter
- A conditional acceptance is not an acceptance: it is a counter-offer that rejects the original offer. Where the parties agreed to use the post, acceptance is complete when the letter is posted, not when it arrives.
- A void contract has no effect (for example no insurable interest, illegality or fundamental mistake), whereas a voidable contract stays in force until the insurer avoids it (for example non-disclosure of a material fact). Breach of a condition relating to one claim lets the insurer decline that claim only; the policy continues.
- Timing of insurable interest: protection and savings at inception only, marine at the time of loss only, general insurance expected at inception and required at the time of loss. A shareholder has no interest in company assets, sentimental value is not financial value, and an expected inheritance is not an interest.
- An independent intermediary has two capacities: agent of the insured when advising, arranging cover and guiding on claims, and agent of the insurer when authorised to accept proposals or collect premiums. An agent acting beyond authority may still bind the principal (apparent authority), but is liable to the principal.
- The duty of disclosure does not renew automatically during the policy: it revives at renewal and on mid-term changes (endorsements), and continues throughout only if the policy says so. An insurer that does not follow up an incomplete or blank answer is treated as having waived it. Materiality is judged from the viewpoint of the prudent insurer, not the policyholder.
- Proximate cause is not the first, the last or the only cause but the dominant one. If the proximate cause is an insured peril, the claim is paid even if some resulting damage is unnamed (such as water damage from fire-fighting); if it is an excluded peril, the claim is not paid.
- Common calculation errors: inverting the average fraction (the correct one is sum insured ÷ actual value), deducting the excess before applying average (it is deducted after), and applying average to liability policies (it does not apply). Benefit policies (personal accident, sickness) are not indemnity policies, so their sums can be added together.
- Contribution and subrogation both support indemnity but differ: contribution is between several insurers (in proportion to sums insured, not equally) and applies only to indemnity policies; subrogation is against a third party after the claim is paid and limited to the amount paid, with any surplus going to the insured. Neither applies to benefit policies.
The other chapters are in the full guide
One purchase · lifetime access · review guide included
7-day review plan
The chapters are spread over 6 days by weight so each day carries a similar load. Day 7 is a full exam.
Day 1 · 36% of the exam
Chapter 1: Understand the main legal principles governing insurance contracts
Day 2 · 18% of the exam
Chapter 2: Understand the nature and main features of risk and insurance
Day 3 · 12% of the exam
Chapter 3: Understand the main regulatory and legal principles applicable to insurance business in Saudi Arabia
Day 4 · 12% of the exam
Chapter 4: Know the main insurance products and related services
Day 5 · 12% of the exam
Chapter 5: Know the structure and main features of the insurance market in Saudi Arabia
Chapter 7: Know key aspects of ethical behaviour and corporate governanceDay 6 · 10% of the exam
Chapter 6: Understand the procedures and policies of the insurance process
Day 7
Full mock exam: 100 questions in 120 minutes, then review the common mistakes in the units where you lost marks.
How many correct answers do you need?
- Pass mark 70%70 correct out of 100
Before you read: see your score today
10 free questions from the main units, no sign-up. Then you know which chapter to start with.
Try 10 free questions and see your levelA look at each chapter
The first three key points of each chapter, as they appear in the guide (in Arabic in the PDF).
Chapter 1: Understand the main legal principles governing insurance contracts
- An insurance contract is a legally enforceable agreement between the insurer and the policyholder…
- An effective acceptance must be final and unconditional; a conditional acceptance is a counter-offer…
- Cancellation
Chapter 2: Understand the nature and main features of risk and insurance
- Risk has several possible definitions
- In insurance the word «risk» is used in two senses
- People perceive and respond to risk differently
Chapter 3: Understand the main regulatory and legal principles applicable to insurance business in Saudi Arabia
- The basic purpose of insurance regulation is to protect consumers, maintain confidence in the…
- Prudential regulation focuses on insurers' safety and financial stability and on preserving the assets…
- Regulatory approaches
Chapter 4: Know the main insurance products and related services
- Insurance products in the Saudi market fall into three categories under Article 3 of…
- Comprehensive motor insurance (for individuals and families) has three sections: Section 1 covers damage…
- Compulsory third-party motor insurance is provided through a unified policy issued by the Insurance…
Chapter 5: Know the structure and main features of the insurance market in Saudi Arabia
- Market participants (2.1)
- Proprietary (limited liability) insurer (2.2)
- Mutual insurer (2.2)
Chapter 6: Understand the procedures and policies of the insurance process
- The general manager or CEO oversees the managers of marketing/sales, technical affairs, accidents and…
- Senior management duties
- The compliance officer is answerable to the board's audit committee and reports to it…
Chapter 7: Know key aspects of ethical behaviour and corporate governance
- Treating customers fairly is the cornerstone of responsible insurance practice: treating customers honestly, fairly…
- The six key elements of fair treatment
- Good customer outcomes are the intended result of fair treatment: customer satisfaction, customer loyalty…
The full guide comes with lifetime access
The full guide (60 pages) is included with lifetime access to this exam, together with every question and full mock exam. Chapter 1 is free for everyone.
Questions about the guide
Is the guide free?
Chapter 1 is free to read on the guide page. The full guide comes with lifetime access to this exam; 7-day access does not include it.
Is it up to date for 2026–2027?
Yes. Unit weights and exam facts follow what the exam body last published, and the last check date is printed in the guide. If the standards change we update the file and buyers download the new version.
Does the guide have questions?
No. The guide covers key points and common mistakes; scoring, weak-area practice and full mock exams are on the site.
Can I read it on my phone?
Yes. A5 pages in a single column, with chapters linked from the contents.
- Pages
- 60
- Edition
- 1448 AH · 2026–2027
- Language
- Arabic
- Last updated
Buy this exam
Pick the access that lasts until your test date.
Included
- Full mock exams: 100 questions in 120 minutes, with a score for every unit
- 541 questions, every option explained with its source
- Practice that starts with your weakest units, plus a review of your mistakes
- Complete Review Guide 2026–2027 (PDF), with lifetime access only
Continue with your Google account and you go straight to the payment page.
You pay on the Waffo Pancake checkout page (in English). The amount is in US dollars and your bank converts it to riyals. One payment with no automatic renewal, by Visa, Mastercard (a mada card with either logo works too), Apple Pay or Google Pay. Your statement shows "WAFFO". Purchases are not refundable.