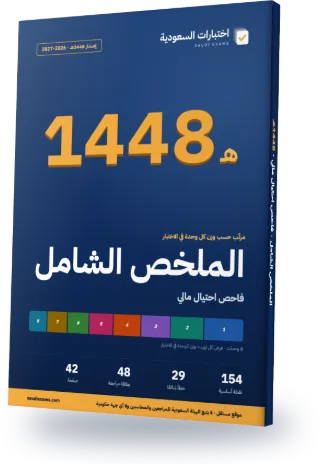
SOCPA Fraud Examiner Complete Review Guide 2026–2027
Every exam topic in a 42-page Arabic PDF, ordered from the heaviest unit to the lightest. The first three chapters alone cover about 46% of the exam questions.
- 42Pages
- 154Key points
- 29Common mistakes
- 48Flashcards
Guide map
Each chapter is one exam unit, ordered by its weight in the real exam.
| Chapter | Unit | Weight | Exam questions | Key points |
|---|---|---|---|---|
| 1 | Financial Statement Fraud | 18% | 18 | 12 |
| 2 | Advanced Fraud Investigation | 15% | 17 | 10 |
| 3 | Asset Misappropriation | 14% | 13 | 11 |
| 4 | Combating Financial Fraud | 13% | 13 | 6 |
| 5 | Other Financial Fraud | 12% | 11 | 11 |
| 6 | Corruption | 11% | 10 | 50 |
| 7 | Conflicts of Interest | 10% | 9 | 45 |
| 8 | Introduction to Fraud | 9% | 9 | 9 |
Chapter 1 in full: Financial Statement Fraud
18% of the exam, about 18 questions. These are its key points, as in the guide.
- Conceptual limits: fraudulent misstatement is intentional, unlike error. It may omit an important disclosure rather than change an amount. It can lower earnings for tax motives or increase them for financing. Earnings management may begin with small adjustments that escalate under pressure. ASA 240, paragraphs 2 and A2.
- Manipulation routes include falsified records and documents, concealed events or transactions, and intentional misuse of measurement, classification, presentation or disclosure principles. Examples include fictitious entries, altered assumptions and shifted recognition dates. A balanced entry does not establish a genuine transaction. ASA 240, A3–A4.
- Effect example: fictitious revenue of 120,000 without cost raises profit by 120,000. Omitting an additional accrued expense of 30,000 produces pretax profit overstatement of 150,000. This follows the assumed entries; do not derive accounting recognition rules from a fraud standard. ASA 240, A3–A4; original application.
The rest of chapter 1, on this page
- Revenue clues: annual totals can hide offsetting changes; compare months, product lines or segments. Receivables outgrowing revenue or year-end earnings inconsistent with operating cash flows warrant explanation, not an automatic fraud finding. ASA 240, paragraph 23, A51 and Appendices 2–3.
- Contract evidence: confirming a balance does not necessarily validate revenue timing. Examine relevant acceptance, delivery, cancellation, return, side-agreement and continuing-obligation terms. Ask people who know the terms and corroborate appropriately. ASA 240, A38 and Appendix 2, Revenue Recognition.
- Inventory evidence: counts and labels alone do not establish contents or condition. Inspecting boxes, hollow stacking and liquid concentration may address misleading quantity or quality. Location/item comparisons and serial-number analysis help identify omissions or duplication. ASA 240, A39 and Appendix 2, Inventory Quantities.
- Risk response: link procedure nature, timing and extent to the disputed information. Specialized technical expertise, changed selection or timing, or more detailed data may help. More copies of the same document do not resolve doubts about its source. ASA 240, paragraphs 30–31 and A34–A38.
- Management override: risk persists despite apparently effective controls. In a financial statement audit, paragraph 33 responses address entries/adjustments, estimate bias and the business rationale of significant unusual transactions. Coverage extends beyond the ledger where consolidation adjustments occur elsewhere. ASA 240,32–33 and A42–A43.
- Entry selection: seldom-used accounts, unusual preparers, poorly explained post-closing entries and round amounts can guide examination; they are not standalone proof. Auditors address period-end entries, consider throughout-period testing and assess multiple locations as appropriate. ASA 240,33(a) and A44–A45.
- Estimate bias: individual decisions may be reasonable yet all favor the same result. Consider estimates collectively. Review prior assumptions for possible bias rather than use hindsight to condemn judgments reasonable on then-available information. ASA 240,33(b) and A46–A48.
- Unusual transactions: evaluate economic purpose, not merely the desired accounting result. Excessive complexity, weak documentation or governance review, and counterparties lacking resources or activity may warrant follow-up. Calling a transaction complex does not establish fraud. ASA 240,33(c) and A49.
- Concluding evaluation: new evidence may require risk reassessment. Repeated small misstatements, or small fraud involving senior management, can qualitatively affect representations and record reliability. Documenting the risk–procedure–evidence link makes the conclusion reviewable. ASA 240,35–38,45–47 and A50–A53.
Common mistakes in this chapter
- Customer amount confirmation does not exclude undisclosed return or cancellation terms.
- Not all financial reporting fraud increases earnings; the objective may be to reduce them.
- Do not treat anomalies, small size or round numbers as final findings; evaluate context and evidence.
- Comparing an estimate with its eventual outcome does not automatically establish fraudulent intent.
- Financial statement auditor requirements are not general investigation powers or universal statutory duties for examiners.
The other chapters are in the full guide
One purchase · lifetime access · review guide included
7-day review plan
The chapters are spread over 6 days by weight so each day carries a similar load. Day 7 is a full exam.
Day 1 · 18% of the exam
Chapter 1: Financial Statement Fraud
Day 2 · 15% of the exam
Chapter 2: Advanced Fraud Investigation
Day 3 · 14% of the exam
Chapter 3: Asset Misappropriation
Day 4 · 13% of the exam
Chapter 4: Combating Financial Fraud
Day 5 · 21% of the exam
Chapter 5: Other Financial Fraud
Chapter 8: Introduction to FraudDay 6 · 21% of the exam
Chapter 6: Corruption
Chapter 7: Conflicts of InterestDay 7
Full mock exam: 100 questions in 150 minutes, then review the common mistakes in the units where you lost marks.
How many correct answers do you need?
- Pass mark 60%60 correct out of 100
Before you read: see your score today
10 free questions from the main units, no sign-up. Then you know which chapter to start with.
Try 10 free questions and see your levelA look at each chapter
The first three key points of each chapter, as they appear in the guide (in Arabic in the PDF).
Chapter 1: Financial Statement Fraud
- Conceptual limits
- Manipulation routes include falsified records and documents, concealed events or transactions, and intentional misuse…
- Effect example
Chapter 2: Advanced Fraud Investigation
- The response plan identifies reporting channels, roles, escalation authority and response SLAs. Source: 6.1(e)(1–4).
- Record the rationale for not investigating a referral; removing it from the queue is…
- The case management system restricts access to authorised users and retains investigative steps, evidence…
Chapter 3: Asset Misappropriation
- Receipts
- Physical and intellectual assets
- Payments
Chapter 4: Combating Financial Fraud
- Governance requires clear responsibilities and oversight by the board and executive management. A counter-fraud…
- Policy sets commitments and requirements; procedures explain operational steps. Both should reflect risks and…
- Risk assessment uses intelligence about fraud methods and examines risks, controls and remaining exposure…
Chapter 5: Other Financial Fraud
- Scams and takeover
- Social-engineering types include credential capture and investment, purchase, invoice and advance-fee scams. Information may…
- Identity and application
Chapter 6: Corruption
- The article expressly includes lawful official acts. Anti-Bribery Law, Article 1; Ministry of Interior…
- Article 1 expressly covers claimed official duties. Anti-Bribery Law, Article 1; Ministry of Interior…
- Article 1 expressly says that intent not to perform does not affect the offence…
Chapter 7: Conflicts of Interest
- Article 26(a) requires the manager to act within assigned powers. Companies Law, Royal Decree…
- Paragraph (b) links the duty to the company’s interest and success. Companies Law, Royal…
- Paragraph (c) requires independent decisions and voting. Companies Law, Royal Decree M/132, Article 26(c)…
Chapter 8: Introduction to Fraud
- SAMA definition
- Framework structure
- Early levels
The full guide comes with lifetime access
The full guide (42 pages) is included with lifetime access to this exam, together with every question and full mock exam. Chapter 1 is free for everyone.
Questions about the guide
Is the guide free?
Chapter 1 is free to read on the guide page. The full guide comes with lifetime access to this exam; 7-day access does not include it.
Is it up to date for 2026–2027?
Yes. Unit weights and exam facts follow what the exam body last published, and the last check date is printed in the guide. If the standards change we update the file and buyers download the new version.
Does the guide have questions?
No. The guide covers key points and common mistakes; scoring, weak-area practice and full mock exams are on the site.
Can I read it on my phone?
Yes. A5 pages in a single column, with chapters linked from the contents.
- Pages
- 42
- Edition
- 1448 AH · 2026–2027
- Language
- Arabic
- Last updated
Buy this exam
Pick the access that lasts until your test date.
Included
- Full mock exams: 100 questions in 150 minutes, with a score for every unit
- 500 questions, every option explained with its source
- Practice that starts with your weakest units, plus a review of your mistakes
- Complete Review Guide 2026–2027 (PDF), with lifetime access only
Continue with your Google account and you go straight to the payment page.
You pay on the Waffo Pancake checkout page (in English). The amount is in US dollars and your bank converts it to riyals. One payment with no automatic renewal, by Visa, Mastercard (a mada card with either logo works too), Apple Pay or Google Pay. Your statement shows "WAFFO". Purchases are not refundable.